Workers' Compensation Insurance

New York requires workers’ compensation for virtually every employee. Eastern Shore Insurance Agency makes compliance painless and helps you manage the cost, not just buy the policy.

Independent Advice

We work for you, not the insurance companies.

Employee-Owned

A team committed to your business and your success.

Six Local Offices

Proudly serving Central & Upstate New York.

When an employee gets hurt

Workers’ compensation protects your employees and your business when work leads to injury.

A warehouse employee injures their back lifting a pallet.

Workers' comp pays their medical care and lost wages.

An office employee develops carpal tunnel over years of work.

Occupational injuries are covered too, not just accidents.

A general contractor demands proof of coverage before your crew starts.

A certificate of insurance from your policy gets the crew on site.

What Workers Compensation Insurance Covers

Workers’ compensation covers your employees when work injures them, and protects your business from the lawsuits those injuries would otherwise become:

Medical care

Treatment for work-related injury and illness, with no cost to the employee.

Lost wages

Partial wage replacement while an employee cannot work.

Disability benefits

Ongoing benefits for lasting impairment.

Death benefits

Support for families after a workplace fatality.

Employer's liability

Defense when an injury turns into a lawsuit against the business.

Who Needs Workers Compensation Coverage

If you have payroll in New York, coverage is not optional, and how your policy is built decides what it costs.

Any New York employer

Required from your first employee, full time or part time.

Businesses that hire subcontractors

Uncollected certificates become your payroll at audit.

Contractors bidding jobs

Proof of coverage is required before crews start work.

Employers watching their experience mod

Classification and claims history drive the premium.

We help contractors, manufacturers, healthcare employers, and restaurants get classified correctly, which is where most overcharges hide.

Need a certificate of insurance fast?

We issue certificates quickly, because a slow certificate can cost you the job. We'll take care of it.

What drives your workers' comp premium in New York
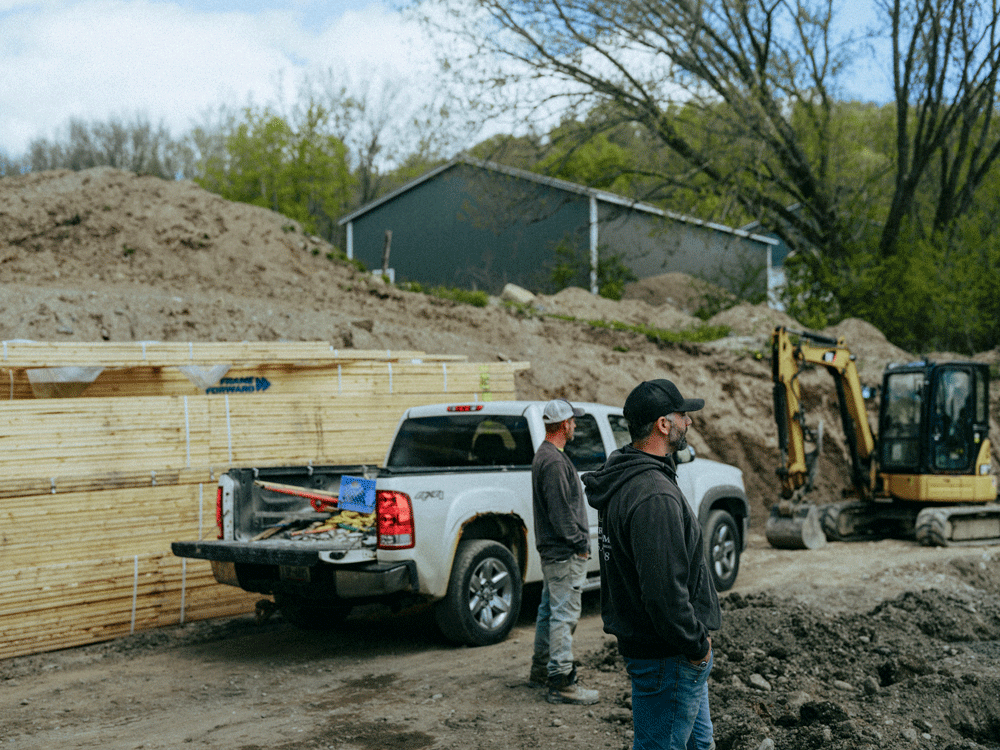
Premium starts with a formula: payroll times the rate for each classification code, adjusted by your experience modification factor. The class codes describe the work your people actually do, and errors here are common; a clerical employee coded as shop labor can double the cost of covering them. The experience mod compares your claims history to businesses like yours, and it follows you from carrier to carrier, so managing it is a multi-year project worth taking seriously. Every workers’ comp policy is auditable. At year end the carrier compares estimated payroll to actual, and the difference becomes a bill or a refund. Clean payroll records, correct class codes, and certificates on file from every subcontractor are what keep audits boring, which is exactly how you want them.

Which coverage do I need?

The three together cover injuries on the job, off the job, and to the public. NY employers generally need all three.

Workers' Compensation

Employees injured on the job. Required in NY.

General Liability

Injuries to customers and other third parties, not employees.

Paid Family Leave & DBL

Off-the-job disability and family leave. Also required in NY.

Why Eastern Shore Insurance Agency

As an independent, employee-owned agency, we shop multiple carriers to find the right coverage at the right value, and we are honest about what you do not need. With six offices across Central and Upstate New York, from Fulton to Waterloo, you get an advisor who knows your community and answers the phone when a claim happens.

Trusted Choice®

100% Employee-Owned

Six New York Offices

Independent Agency
Workers Compensation FAQs

Quick answers to common questions from New York employers.
Yes, for virtually all employees, with very narrow exceptions. Operating without it brings fines that accumulate fast, personal liability exposure, and stop-work orders. If you have payroll, get covered.
Premium is driven by your payroll, your classification codes, and your experience rating. Misclassification is the most common reason businesses overpay, and it is the first thing we check when we quote.
No. Off-the-job disability is what New York’s DBL coverage is for, and it is also required. Many employers do not realize they need both until an audit letter arrives.
Sometimes, and getting it wrong is expensive. New York looks at the actual working relationship, not the label. Collect certificates from every sub, and talk to us about how your operation is structured.

Have any questions?

Our local team can help you find the right coverage for your business in New York.
Related coverages

General Liability

Everyday protection for your business.

Paid Family Leave & DBL

New York's required income protection, handled.

Commercial Umbrella

Extra liability protection when you need it most.

Commercial Auto

Coverage for the vehicles that do the work.

Industries We Serve

Insurance solutions built for the way you work

We partner with businesses across a range of industries to help manage risk and drive growth.